Thrown objects
A mower deck can launch a stone through a window, a windshield or a person at speed. This is the most frequent claim in the trade by a wide margin, and it happens on properties where you did nothing else wrong.

Contractor insurance
Lawn and landscape operations run a lot of equipment across a lot of properties in a short season. The exposures that matter most are usually high-frequency and low-cost, with two significant exceptions: chemical application and winter work.
The range here is unusually wide, from a two-person mowing route to design and installation crews running heavy equipment. Describing what you actually do matters.
A mower deck can launch a stone through a window, a windshield or a person at speed. This is the most frequent claim in the trade by a wide margin, and it happens on properties where you did nothing else wrong.
Applying product introduces drift, overapplication and misapplication exposures, plus licensing obligations that sit outside insurance. Many general liability policies contain pollution exclusions that interact with this work in ways people do not expect.
Winter work changes the business you are insuring. Slip and fall claims arising from a lot you plowed or salted can arrive months later, and the standard of care expected is often written into the contract you signed in October.
Equipment rolling off a ramp, a trailer coming loose, or a gate left down accounts for a steady share of losses. Trailers are also the single most common thing left off a policy.
Hardscape and grading work can shift water onto a neighbor's property or fail structurally. These claims arrive long after the invoice is paid and look very different from a broken window.
Mowers, trimmers and blowers left on an open trailer overnight are among the most frequently stolen items in any trade. Where that equipment is covered, and whether it is covered off premises, is worth confirming.
Liability coverage for a lawn and landscape operation is built around damage done to property you were not hired to touch, which in this trade happens constantly and usually at low cost. For this trade, two questions do the most work: whether you apply chemicals, and whether you perform snow and ice services. Both are commonly addressed by specific exclusions or endorsements, so the answer should not be assumed in either direction.
If you have employees, expect the conversation to cover seasonal and part-time staff, which this trade uses heavily. Cuts, heat, lifting and equipment contact drive the exposure. Because payroll swings sharply across the season, an accurate estimate up front tends to mean fewer surprises when the audit comes around.
Pickups, dumps and the trailers behind them, plus plow trucks in winter. Towing, loading and the number of people permitted to drive are the usual points. Adding a plow changes how a truck is used and should be reported rather than assumed.
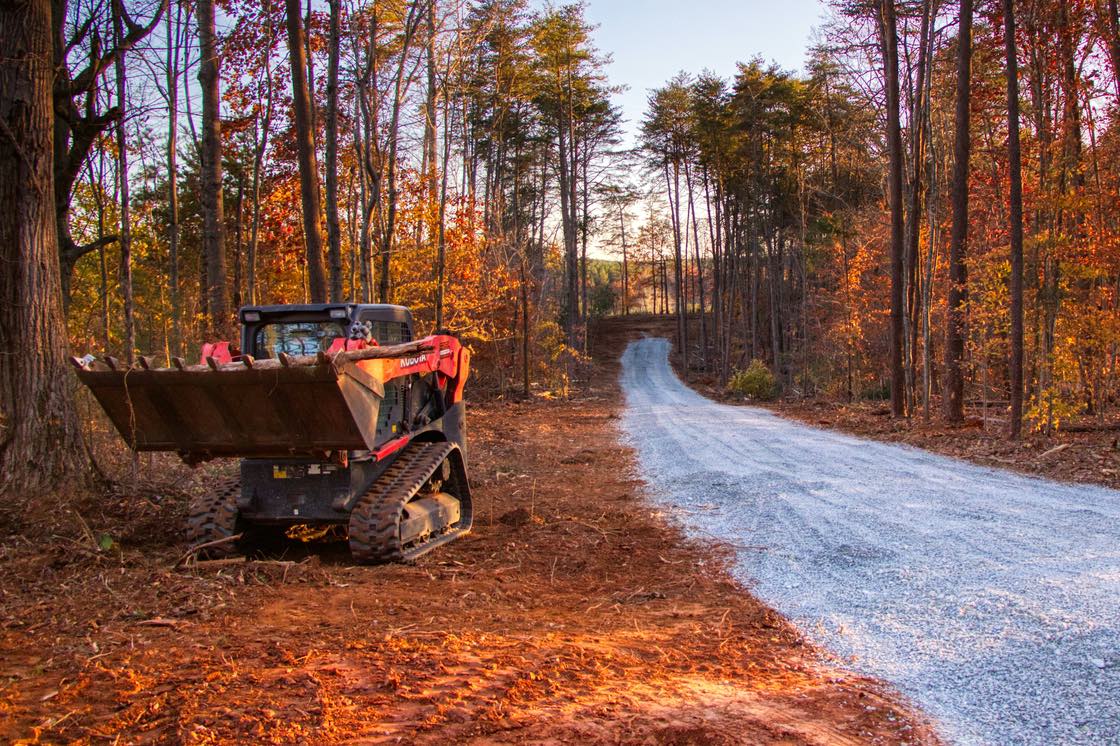
Mowers, trimmers, blowers, skid steers and plows are usually handled as equipment rather than under a liability policy. Coverage while equipment is on a trailer, at a customer site, or parked at your yard overnight can each be treated differently, and chemicals in storage raise their own questions.
This page is general information, not legal, safety or coverage advice. What a policy actually covers depends on your business operations and on the policy, carrier, terms, conditions, limits and exclusions that apply. Nothing here confirms eligibility or guarantees that any coverage is available to you.
It is at least worth reporting so the decision is made with the facts in front of you. These claims are frequent and usually modest, but a pattern of unreported incidents can create problems later. Whether it makes sense to submit a small claim is a separate conversation about deductibles and renewal, and we are happy to have it.
Do not assume it does. Snow and ice work is commonly excluded or handled by endorsement on landscape policies, and slip and fall claims from winter work can surface long after the season ends. If you plow, it needs to be part of the conversation before the first snowfall.
Generally yes. Application work interacts with pollution exclusions and with licensing requirements that sit outside your insurance policy entirely. If you apply product, say so up front so the policy reflects what you actually do.
Call or text the office, or send a request and we will get back to you.
Dassel State Insurance Agency is based in Dassel and works with contractors throughout Minnesota.